U.S Dollar continue to strengthen, Gold hits two-month low
Beginning with yesterday market developments, the U.S Dollar resumed its rally against the G10 currencies as FED rate hike is on the table again. The Dollar index traded higher on Tuesday and has reached two-week high at 96.14 boosted by a strong increase in the consumer confidence index during the month of August.
The Japanese Yen plunged by 1.13% against the Greenback to reach 103.10, highest level since July 29. In the meantime, both the Euro and the British pound extended last Friday decline to stabilize at 1.1140 and 1.3070 levels respectively.
In the equity market, the Dow fell by 49points, while the S&P500 was off 0.2%. Gold retreated to two-month low at $1310 per ounce, meanwhile, Oil prices settled down 1.34% at $46.35 on the back of a strong Dollar.
Now let us have a look at the technical picture of the Euro, the British pound, Gold and the U.S Dollar index.
EUR/USD
The Euro resumed its decline after bears managed to push prices below 1.1240 hourly support. As of now, the trend remain bearish in the near-term, and a continuation to the downside is likely in the coming hours. However, when looking at momentum indicators, the pair is clearly oversold and a bounce can happen soon. Technically, the drop should find strong demand around 1.1110-1.1080, from where we expect to see the beginning of at least three corrective waves higher.
In the daily chart, the single currency remain under pressure below 1.1365 peak, meanwhile, prices are likely to test the 61.8% Fibonacci retracement of the entire recovery that began from 1.0910 low which stands at 1.1085. Consequently, the recent sell-off may slow down once prices get there.
Support: 1.1120-1.1085-1.1055
Resistance: 1.1160-1.1190-1.1205
GBP/USD
The British pound keep fighting for a clear direction in the near-term and volatility is likely to increase in the coming hours, ahead of the U.S Non-farm payrolls due later this week.
From a technical standpoint, the Sterling remain positive in the hourly chart as far as 1.3025 support is in place. However, the current market environment is in favor of the U.S Dollar, which can keep the upside potential limited in this pair.
In the near-term, the focus should be 1.3070 support as a break below it will bring the bearish pressure and can send the pair to as low as 1.3025 in the next days.
In the flipside, a daily close above 1.3157 level can be the trigger for a move back up towards 1.3170/95 resistance zone will offer fresh selling opportunities for bears and another wave lower to be seen.
Support: 1.3072-1.3025-1.2975
Resistance: 1.3157-1.3170-1.3195
GOLD
After several attempts to break above 1357 hourly resistance that failed, prices succeeded to break below the support zone of $1333/1328 in the daily chart, which cleared the path for a re-test of the daily support of $1305.
Technically, gold turned bearish in the near-term as prices has shown four consecutive lower highs (1375-1367-1357-1342) from the yearly peak of $1375, which reinforces the probability of further weakness in the coming days. As of now, $1325 represents the short-term resistance level and as far as prices keep trading below it, further weakness is here to stay in the coming hours.
To conclude, gold remain under pressure and the upside potential is likely to be limited, while another towards 1300 psychological support is imminent.
Support: 1305-1300-1287
Resistance: 1316-1322-1325
Dollar index
Looking at the U.S Dollar price action ahead of the U.S Jobs report scheduled for Friday. The Greenback continue to strengthen as FED rate hike bets increased significantly, the sentiment shifted towards buying the U.S Dollar in the recent days.
Technically, prices overtook 96.00 handle, which keeps the near-term outlook bullish for the U.S Dollar, in addition, the break above this resistance should expose 96.50 area in the coming days, and from where strong sellers may appear. From a larger perspective, the Dollar keep trading sideways in the weekly chart, as investors remain skeptical about the date of the next interest rates hike. Consequently, volatility can persist in the near-term unless we see a clear break above 97.65 peak or below 93.00 weekly support.
Meanwhile, we can see that bulls managed to preserve the higher lows structure that began from 92.95 low, which may lead to further gains in the Greenback especially if a daily close above 96.50 level happens.
A resurgent Dollar rattled the financial markets on Wednesday with most currencies kneeling to the greenback following the firm ADP Non-Farm employment figure of 177k which heightened hopes over the Federal Reserve raising rates in 2016. With US labour repeatedly displaying signs of resilience in a period of global uncertainty, part of the prerequisites for the Fed to take action this year may have been achieved. This has been a solid week for the Dollar and the string of positive economic data release could entice bulls to send the Dollar higher as optimism rises over the Fed breaking its tradition of central bank caution.
Although there have been ongoing talks of there being a live meeting to raise US rates in September, such could be slightly abrupt with the possibility that the Fed will digest further positive data to support hiking rates in December. With an increasing focus on US data as an attribute to fulfil the conditions of a rate increase, much attention may be directed towards Friday’s NFP report. If the Non-Farm payroll for August exceeds expectations, then the central bank may be offered another compelling reason to pull the trigger in December.
The rising optimism over the Fed taking action this year has propelled the Dollar Index above 96.00. This Index is turning bullish on the daily timeframe as prices are trading above the 20 SMA. Previous resistance around 96.00 could transform into a dynamic support which encourages buyers to send prices towards 96.50.
UK Manufacturing PMI in focus
Sterling bulls made a valiant effort to reclaim control on Wednesday with the GBPUSD lurching towards 1.3150. While bulls may be commended on their efforts to elevate the GBPUSD higher, it has nothing to do with an improved sentiment towards the Sterling but Dollar instability from the fluctuating expectations over the Fed taking action this year. Sterling remains chained by the Brexit uncertainty which has haunted investor attraction towards the currency, while speculations of further easing by the BoE continue to entice bears to install repeated rounds of selling. Investors may direct their attention towards the UK Manufacturing PMI for August which may offer some clarity on how the manufacturing industry is faring post-Brexit. A further contraction in manufacturing may rekindle fears over a slowdown in economic momentum consequently bolstering hopes of the BoE easing further in 2016. On the other hand, the Sterling could be offered a lifeline if an upbeat manufacturing PMI release quells easing speculations.
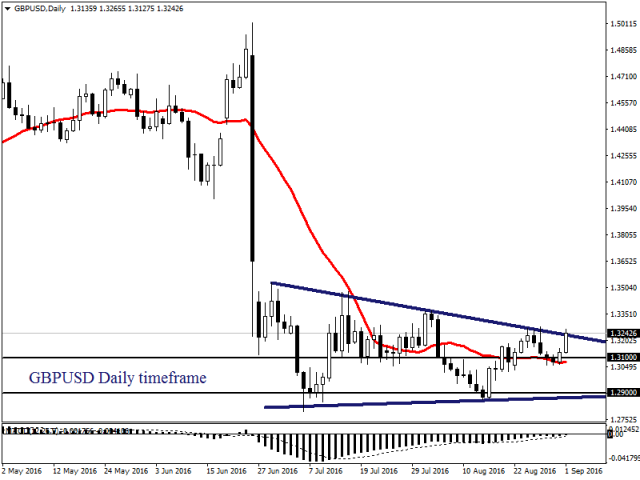
The GBPUSD has been flung onto a chaotic roller coaster ride with prices sharply swinging between losses and gains amid Fed hike hopes. Sterling remains heavily pressured and the divergence in monetary policy between the BoE and Fed could entice sellers to attack the GBPUSD. From a technical standpoint, prices are trading below the daily 20 SMA while the MACD has crossed to the downside. A breakdown below 1.3100 may open a path towards 1.2900.
Commodity spotlight – Gold
Gold remains under immense pressure with the metal breaking below the firm $1315 support as the growing expectations over the Fed raising US rates this year continues to encourage bears to install heavy rounds of selling. It should be kept in mind that although Gold is very attractive in times of uncertainty, the metal is zero yielding and also priced in Dollars which make it very vulnerable to rate hike speculations.
Friday’s NFP could be a critical attribute which will decide where Gold trades towards in the coming weeks with a strong employment report potentially leaving prices vulnerable to heavy losses. From a technical standpoint, prices are trading below the daily 20 SMA while the MACD has crossed to the downside. Previous support at $1315 could transform into a dynamic resistance that encourages a further decline towards $1285. While the technicals are currently firmly bearish, an extremely weak NFP would destroy the hopes of the Fed raising rates in the short term and could offer Gold a lifeline.
Sterling displayed an incredible rebound during trading on Thursday with the GBPUSD surging towards 1.3265 following August’s blockbuster manufacturing PMI of 53.3 which instantly dispelled the ongoing Brexit fueled concerns. UK Manufacturing has hit a 10-month high clawing out of contractionary territories aided by a vulnerable Sterling that helped bolster export orders and input costs. While the rebound in manufacturing is unquestionably encouraging, investors should still keep in mind that it may be too early to gauge the ramifications of Brexit to the UK with more time needed for a clear picture. Although Sterling may enjoy further gains in the short term as expectations erode over the BoE easing further, the lingering Brexit uncertainty should cap upside gains in the longer term.
From a technical standpoint, Sterling bulls were offered a lifeline and the GBPUSD has already lurched over 130 pips to the upside. Prices are trading above the daily 20 SMA while the MACD is in the process of crossing to the upside. While bulls may seem to be in control on the daily timeframe, a solid NFP on Friday could swiftly quell the uptrend with prices trading back towards 1.3100.
Commodity spotlight – WTI Oil
WTI Oil descended towards three-week lows at $44.60 on Thursday as the persistent concerns over the excessive oversupply of oil in the global markets haunted investor attraction towards the commodity. It is becoming increasingly clear that investors have digested the oversupply reality with the fading optimism over OPEC securing a freeze deal in September’s informal meeting enticing sellers to attack further. U.S crude stockpiles have risen consecutively while OPEC heavyweights such as Saudi Arabia and Iraq continue to pump incessantly into a market that is already heavily saturated. WTI Crude remains fundamentally bearish with further declines expected as the combination of supply fears and soft demand encourages bears to install rounds of selling. The sharp breakdown below $46 may open a clean path towards $44.00.
A sense of anticipation has firmly gripped the financial markets on Friday as investors await the Non-Farm payrolls report for August which could provide clarity on when the Federal Reserve plans to raise US rates in 2016. Global stocks remain mixed with most major markets on standby as anxious investors observe from a distance ahead the market shaking employment report. Asian equities have already drifted lower on Friday and this caution could trickle into Europe consequently leaving European stocks vulnerable to losses. Wall Street was punished on Thursday by the downbeat U.S manufacturing data that rekindled concerns over the US economy with further losses expected as investor jitters intensify ahead the NFP.
The over-extended stock market rally may be displaying signs of exhaustion with September being a potential month where bears emerge from hibernation. Although the heightened expectations of the Fed raising US interest rates has somewhat elevated global sentiment, the persistent concerns over the health of the global economy are still lingering in the background. Prolonged periods of depressed oil prices have eroded investor risk appetite while uncertainty is still a recurrent theme which has left market participants on edge. With volatility making a comeback it could take an unexpected catalyst to trigger a steep stock market selloff. Conventional wisdom holds that a strong Dollar is problematic for stocks which should keep investors alert as hopes heighten over the Fed taking action this year.
UK Construction PMI in focus
Sterling bulls were gifted a lifeline on Thursday with the GBPUSD lurching towards four-week highs above 1.3300 following August’s solid manufacturing PMI of 53.3 which alleviated the Brexit fuelled fears. Sterling weakness from the persistent Brexit uncertainty helped uplift export orders and input costs consequently propelling the UK manufacturing to fresh 10 month highs. While this data was quite impressive, it still remains too early to come to a conclusion with more time needed to weigh the impacts of Brexit to the UK economy.
Investors may direct their attention towards the UK construction PMI which if also exceeds expectations could provide the Sterling another welcome boost. Sterling could accumulate further gains in the short term as the positive data diminishes expectations over the BoE easing further. In the longer term, upside gains could be capped as the Brexit uncertainty persistently haunts investor attraction towards the currency.
From a technical standpoint, Sterling bulls were unchained on Thursday with the GBPUSD rising over 170 pips in a single trading day. Prices are trading above the daily 20 SMA while the MACD has crossed to the upside. Although bulls may be currently in control, a positive NFP figure which bolsters hopes over the Fed raising US rates could cause the GBPUSD to tumble back down towards 1.3100.
Soft US Manufacturing pressures Dollar
The Dollar was left pressured on Thursday following the unexpected contraction in U.S manufacturing which rekindled concerns over the health of the US economy. Manufacturing slipped into contractionary territory at 49.4 for the first time since February consequently dimming hopes over the Fed raising US interest rates in September. Although the manufacturing report was somewhat disappointing, overall data from the US has displayed signs of economic stability which has kept hopes alive for the Fed to act this year. Investors may direct their attention towards Fridays heavily anticipated NFP report which if exceeds expectations could renew optimism towards the Federal Reserve breaking the trend of central bank caution.
It may take an extreme anomaly in Friday’s NFP report to abruptly cool the heated expectations over the Fed raising rates at least once this year. A healthy figure above 180k which displays some stability in the US labour force may be enough to keep hopes buoyed over the central bank pulling the trigger in 2016. A figure below 150K could renew concerns over the health of the US economy and potentially erode optimism towards September being a “live” meeting to act. In extreme cases, a repeat of May’s dismal employment report figure of 38k could temporarily sabotage all efforts taken by the Fed to act.
Dollar bulls are still in control and the Dollar Index is still bullish on the daily timeframe. Prices are trading above the daily 20 SMA while the MACD has also crossed to the upside. A decisive breakout above 96.00 could open a path towards 96.50.
WTI Oil breaks below $44
WTI Oil was left vulnerable to extreme losses during trading on Thursday with prices breaking below $44 as investors discounted the possibility of OPEC securing a freeze in September’s informal meeting. Although OPEC may be commended on their ability to exploit the oil price sensitivity by creating speculative boosts in oil prices, it has come at a very heavy cost. Fears over the excessive oversupply in the markets continue to haunt investor attraction towards the commodity while concerns over slowing demand have capped upside gains. Crude oil stocks piles continue to rise while OPEC members incessantly pump to reclaim market share. The ingredients of a bear trend are present and September’s informal meeting could be the catalyst needed to send WTI lower towards $40.
Commodity spotlight – Gold
Gold was elevated slightly on Thursday following the soft US manufacturing data which eroded some expectations over the Fed raising US interest rates this year. Despite the lifeline provided, the metal has been under pressure today with prices trading towards $1310 as anticipation mounted ahead of the NFP. Gold has been very attractive in times of uncertainty and unease but the metal is zero yielding and also priced in Dollars which make it quite vulnerable to rate hike speculations.
Friday’s NFP could be a critical catalyst which will decide where Gold trades towards in September with a firm employment report leaving the metal open to steep losses.From a technical standpoint, prices are trading below the daily 20 SMA while the MACD has crossed to the downside. Previous support at $1315 could transform into a dynamic resistance that encourages a further decline towards $1285.
While the technicals on the daily are currently firmly bearish, an abysmal NFP that diminishes expectations of the Fed raising rates could propel Gold higher.
U.S Dollar consolidates as NFP figures disappoints
The Dollar traded lower on Friday after the recent NFP figures pushed investors to re-evaluate their rate hike expectations.
The U.S economy added only 151 000 new jobs in August compared to estimates of 180 000. This is a significant drop from July figures, which were at 275 000. In the meantime, the unemployment rate stabilized at 4.9% while it was anticipated at 4.8%. Meanwhile, the wages slowed down in August as the average hourly earnings retreated by 0.1% compared to 0.3% previously.
After the release of these disappointing figures, the U.S Dollar immediately plunged across the board (1.3350 against the British pound, 1.1250 against the Euro and 102.80 versus the Japanese Yen) before to trim some losses by the time of the weekly close.
The rate hike probabilities decreased significantly as a move in September has become off the table for the time being. The latest Bloomberg survey show a 32% probability only for September, 36.4% for October, and 59.0% for December.
Looking at the U.S Dollar recent price action after the U.S Jobs report. The Greenback continue to strengthen as FED rate hike is expected before the end of 2016, the sentiment shifted towards buying the U.S Dollar in the recent days.
Technically, prices dropped into a short-term corrective wave and has retraced exactly 50% from the last rally from 94.00 support, this level stands at 95.15 and from where we have seen a strong bounce in the dollar which keeps the near-term outlook bullish for the Greenback. Moreover, prices managed to overtake the bearish trend line in the daily chart and as of now, a move higher in the direction of 96.50 resistance area is likely in the coming days.
In the flipside, 95.15-94.88 levels are considered as a strong support zone for the near-term price action and the downside potential remain limited above this support. Therefore, prices should continue to trade higher during next week as bulls continue to maintain the control.
From a wider angle, the Dollar keep trading sideways in the weekly chart, as investors remain skeptical about the date of the next interest rates hike. Consequently, volatility can persist in the near-term unless we see a clear break above 97.65 peak or below 93.00 weekly support.
Meanwhile, we can see that bulls managed to preserve the higher lows structure that began from 92.95 low, which may lead to further gains in the Greenback especially if a daily close above 96.50 level happens as mentioned above.
WTI Oil displayed an incredible rebound on Monday with prices piercing above $46 after Russia and Saudi Arabia pledged to stabilise the saturated oil markets. With Russia and Saudi Arabia being the largest oil producers in the world, the prospects of a potential deal formed by these powers has generated sharp speculative boost in prices. Although there have been talks that the cooperation marks a “new era” which would have a “critical significance”, it still does not change the current oversupply woes which have made Oil fundamentally bearish. While the short term gains from freeze deal speculations have been impressive, the commodity remains pressured with further losses expected if September’s informal OPEC meeting concludes without an effective deal.
Oil’s woes remain the oversupply fears which have haunted investor attraction and a freeze deal at the current record output levels may do little to ease these anxieties consequently weighing heavily on investor risk sentiment. For Septembers meeting to have a significant impact on Oil prices there needs to be a solution to remove the excessive oversupply but the question is are other OPEC members willing? It should be kept in mind that OPEC’s crude production jumped to a record high in August while Iran remains on a self-fulfilling quest to reclaim lost market share. The cartel faces an obvious prisoner’s dilemma from cutting production which may entice US shale to jump back into the markets.
WTI is still technically bearish on the daily timeframe as prices are trading below the daily 20 SMA while the MACD trades to the downside. $46 could act as a significant resistance which encourages bears to drag prices back down lower towards $44. A decisive breakdown below $44 could encourage a steeper decline lower towards $40.
Commodity spotlight – Gold
Gold was propelled higher last week with the metal charging towards $1330 following the soft U.S labour report which dented expectations over the Federal Reserve raising US interest rates in 2016. This yellow metal remains highly sensitive to US rate rise speculations and with current hopes fading, further gains could be accumulated in the short term. With concerns still lingering over the health of the global economy, Gold could regain some allure as investors flock to safe-haven safety. Although prices are still technically bearish on the daily timeframe, Dollar weakness could propel the metal back above $1345 consequently handing bulls back control. From a technical standpoint, Gold needs to strongly break above $1330 to signal a further incline towards $1345.
The Australian dollar has come managed to climb the charts on the back of USD weakness today, but all is not as rosy as it seems and it's becoming clear that the Australian economy is really struggling after all three PMI readings this month fell below expectations. Manufacturing and Services PMI readings showed large drops which had many worried, and now Construction PMI data out today came in at 46.6 (51.6 prev) showing a contraction in the sector. This is nothing new that the Aussie economy is struggling but it does lend weight behind the idea that the Reserve Bank of Australia should look to prop up the economy and an interest rate cut may be needed here. However, the property market will be a major concern with housing approvals jumping on the most recent reading on weaker interest rates over all.
Technically on the charts the AUDUSD has broken out of the bearish widget that it was forming and has pushed up to resistance at 0.7690 and is looking very unlikely to continue this movement unless we see further USD weakness. For me a pullback is more likely on the cards given the weak data that continues to come out of the Australian economy and shows no signs of letting up, so support at 0.7638 has become all the more tangible in recent times. I would also watch the 50 day moving average which has been acting as dynamic support and resistance as well for the market.
The New Zealand dollar was spoken about heavily yesterday, and for good reason as pressure was finally building and it seemed that we may indeed see a break out for the NZDUSD. After today it can be confirmed that the bulls have looked to take back control after markets pushed through the ceiling of resistance at 0.7311. This has been lead in two parts, firstly by the shocking ISM non-manufacturing PMI which has shown a bigger drop than anyone expected in the USA to 51.4 (55.0 exp). This has had a large impact as USD selling as a whole was heavy today. Additionally we saw positive data out of the NZ market as manufacturing sales q/q lifted to 2.2% (-2.6% prev), and will be a welcome note to the NZ economy which has for the most part been struggling as of late and looked like further rate cuts may be on the horizon. It will be hard to justify them now given the recent economic turnaround, but the NZD will remain a concern for the RBNZ and it's likely it will look to talk down the high flying NZD.
Glancing at the technical's and as I mentioned yesterday the next level of resistance is looking likely at 0.7475. Any pulls backs are a real possibility after yesterday's move, but I would anticipate support to now be formed at 0.7311 and the likelihood that the previous bullish trend line will hold up further movements. The 20 day and 50 day moving average are also providing support and are just below the trend line and likely to prop up any further drops and assist bulls.
Dollar bears were unleashed on Tuesday following the disappointing U.S ISM services data which dented hopes over the Federal Reserve raising US interest rates in September. The ISM non-manufacturing PMI for August came in at 51.4, making it the lowest since February 2010 consequently rekindling concerns over the health of the US economy. September has been a painful start for the Dollar bulls with the recent soft domestic economic releases challenging the bullish sentiment which initially elevated the Dollar. If US data continues to miss expectations then talks of September being a live meeting to raise rates could be thoroughly discounted with a move in December hanging on a thin line.
The Dollar Index plummeted on Tuesday with prices breaking below 95.00 as hopes over the Fed breaking the tradition of central bank caution faded into the distance. Prices are trading below the daily 20 SMA while the MACD has also crossed to the downside. If the bearish momentum holds then the Dollar Index could trade lower towards 94.20.
Sterling bulls unchained
Sterling has enjoyed an extended period of gains with the GBPUSD charging to eight week highs at 1.344 as the combination of impressive UK economic data and Dollar weakness attracted bulls to install heavy rounds of buying. Sterling has had a good run with the string of positive PMI releases over the past week dispelling ongoing concerns that the EU referendum outcome may have an immediate negative impact on the UK economy. Although further gains in the pound may be accumulated in the short term as expectations diminish over the BoE unleashing further stimulus measures, it may be slightly early to come to a decisive conclusion with more time needed to weigh the impacts of Brexit to the UK economy.
Investors may direction their attention towards the UK manufacturing production data which could provide additional clarity on how the sector has fared post-Brexit. A release which follows the same positive pattern and exceeds expectations could reinforce further confidence into the UK economy consequently propelling the Sterling higher.
The BoE inflation report hearing may be the event which seizes centre stage today where Governor Carney will testify to the Treasury Select Committee. Mark Carney may likely reiterate his dovish mantra on the health of the UK economy while potentially suggesting of further stimulus measures in the coming months to retain economic stability. While questions may be asked if the BoE acted too swiftly to easing monetary policy post Brexit following the recent string of positive data, it still remains too early to gauge the effects of Brexit to the UK.
Commodity spotlight – Gold
Gold displayed an incredible appreciation on Tuesday with prices lurching towards $1352 following the soft US ISM services data which eroded optimism over the Fed raising US interest rates in September. The sharp uplift was complimented with Dollars vulnerability which provided a solid platform for bulls to install heavy rounds of buying. With hopes fading over the Fed stepping forward to raise rates in September, this yellow metal could be open to further gains moving forward. From a technical standpoint, prices have turned bullish on the daily timeframe and the breakout above $1345 could open a path towards $1355.
The Canadian dollar managed to buck the trend and rise up the charts today against the USDCAD as despite keeping rates on hold at 0.50% and Ivey PMI slipping to 52.3 (55.9 exp) the CAD remained firm. But this was not just purely on the back of positive data, instead it was helped also by oil prices managing to rise and the Canadian dollars correlation with oil prices also helping to drive home the movements that we saw against the USD. Oil's jump was led in part by talk of a large drawdown in US crude oil inventories, but at the same time it was announced that 3 billion barrels had been found in West Texas via shale and this was likely to put into production in the next few years. For me the Canadian dollar continues to be a popular currency to trade with its strong swings being attractive to traders
Looking at chart movements it's clear that a bullish trend line on the daily chart is having a large impact for traders, and any movements lower are likely to find support at this key area. The push back up to resistance at 1.2913 lacked momentum today, but a touch on the trend line could lead to a push through this level with some serious volatility. If the trend line was likely to break then I would expect a push down to support at 1.2568 as traders look to take the wind out of the bulls.
The Australian economy had a bad day yesterday when it came to economic data and today was not to different with GDP figures showing a drop much worse than expected. GDP q/q was down to 0.5% (0.6% exp) and GDP y/y slipped to 3.3% (3.4% exp). By any standards this is still a strong reading for any developed economy, but in the case of Australia it shows the economy consistently slowing down at present with sluggish capital spending and all the PMI figures showing a slowdown it's a matter of time before the Reserve Bank of Australia talks down the AUD over the issues that are at hand. With all of the current issues a rate cut will also being priced in by the market, and bets are likely to increase with further negative data that the rate cut will come sooner rather than later. There is little hope in waiting for a US rate hike at this stage to help push the AUD down, as data continues to be a mixed bag throughout the USA.
The AUDUSD has so far stalled from going any higher at 0.7690 as it acts as a strong level of resistance in the market. At this stage given the negative fundamental data it's likely that the bears will use technical's to play the AUDUSD down in the long run, while also betting on the Reserve Bank of Australia to say something. Support levels can be found at 0.7635 and 0.7582, with traders likely to targets these levels as the AUDUSD falls and the bears look to make the most of the negative fundamental data we are seeing.
The Euro was flung onto a chaotic rollercoaster ride on Thursday following the European Central Bank’s decision to keeping its monetary policy stance unchanged despite the worrying state of the European economy. Official interest rates were left unchanged while monthly asset purchases of $80 billion were confirmed to run until the end of March 2017 which left investors empty handed. With uncertainty still a recurrent theme in the markets, most central banks have adopted a stance on inaction and such was displayed in today’s ECB meeting. Although Draghi pledged that the ECB would act by using all instruments available within its mandate to bolster Eurozone growth, this may have fallen on deaf ears.
It is becoming increasingly clear that the Eurozone is entangled in a losing battle with faltering growth while static inflation levels continue to question the ECB’s credibility. Although Draghi also suggested that the economic recovery in Europe is likely to be dampened by the UK’s Brexit vote, this was still not enough to prompt the central bank to act. While Draghi’s dovish rhetoric may have opened doors for an extension to bond buying program beyond March 2017, the visible disappointment could propel the Euro higher. Sentiment remains bearish towards the Eurozone and today’s inaction may spark further questions over the central bank’s ability to jumpstart Eurozone growth.