BTC USD 81,457.9 Gold USD 4,378.12
Time now: Jun 1, 12:00 AM

Smartproptrader - smartproptrader.com

MARKET COMMENTARY


Market Wrap: Stocks, Bonds, Commodities

On Monday, the U.S. equity market was closed to observe the Martin Luther King Day.

Meanwhile, European stocks were broadly higher. The DAX 40 rose 0.74%, the CAC 40 increased 0.74%, and the FTSE 100 was up 0.89%.

U.S. WTI Crude futures fell $1.05 to $78.81 a barrel.

Gold price eased $4 to $1,916 an ounce.

Market Wrap: Forex

The U.S. dollar index edged up 0.2% to 102.38.

EUR/USD slipped 10 pips to 1.0820. Germany's January ZEW economic sentiment index, due later in the day, is expected at -16.0

GBP/USD dropped 32 pips to 1.2195. Later today, the U.K. jobless rate for the three months to November is expected to be steady at 3.7%.

USD/JPY rose 68 pips to 128.55.

USD/CHF lost 4pips to 0.9265.

Commodity-linked currencies were broadly lower against the greenback. AUD/USD fell 16 pips to 0.6952, while USD/CAD added 19pips to 1.3415. Investors would keep an eye on China's fourth quarter gross domestic product due later today, with a year-on-year growth of 1.5% expected.
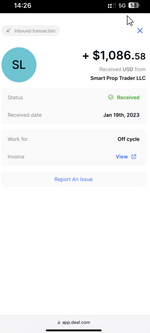
 
Payout
2023-01-17 12_35_15-IMG_4173.png (284×614).png
 
MARKET COMMENTARY


Market Wrap: Stocks, Bonds, Commodities

On Tuesday, U.S. stocks closed in mixed territory. The Nasdaq 100 rose 15 points (+0.14%) to 11,557, while the S&P 500 fell 8 points (-0.20%) to 3,990 and the Dow Jones Industrial Average declined 391 points (-1.14%) to 33,910.

Shares in the Automobiles & Components (+5.24%), Semiconductors & Semiconductor Equipment (+0.77%), and Consumer Services (+0.75%) sectors were the top performers while shares in the Telecommunication Services (-1.88%), Retailing (-1.36%), and Insurance (-1.15%) sectors underperformed the most during the trading session.

On the U.S. equity front, Chinese electric vehicles maker XPeng (XPEV) fell 6.31% after slashing prices on its models in China. Oppositely, Tesla (TSLA), the electric-vehicle maker, jumped 7.43% as data released from China Merchants Bank International indicated daily sales increased 76% between January 9 and January 15 when compared to the same period a year ago.

Meanwhile, Morgan Stanley (MS) climbed 5.91% as the investment firm topped fourth-quarter profit estimates following strong returns at its trading business, while its peer Goldman Sachs (GS) slid 6.44% after top- and bottom-line figures missed estimates. Also, Emerson Electric (EMR), a producer of electronic and electrical products, fell 6.82% as it announced a 7 billion dollars takeover offer for National Instruments (ANTI).

On the U.S. economic data front, January's Empire State Manufacturing Index was posted at -32.9, against -5.2 initially estimated.

The U.S. 10-year Treasury Yield added 4.8 basis points to 3.551%.

European stocks were mixed, as the Dax 40 rose 0.35% and the Cac 40 was up 0.48%, while the FTSE 100 fell 0.12%.

U.S. WTI Crude Future gained $1.2 to $81.03.

Gold was down $7 to $1,909.

Market Wrap: Forex

The U.S. dollar index added 0.2% to 102.39.

EUR/USD dropped 32 pips to 1.0788, following media reports suggesting that the European Central Bank might slow its rate hike pace in February. Meanwhile, Germany's January ZEW economic sentiment index was released at 16.9 vs -16.0 expected.

GBP/USD jumped 92 pips to 1.2286. The U.K. jobless rate for the three months ending November remained steady at 3.7% as expected. On the other hand, December consumer price index will be released later in the day, with a year-on-year growth of 10.5% expected.

USD/JPY fell 40 pips to 128.18. Investors would watch closely the Bank of Japan's monetary policy decision due later in the day, amid speculation on further tweaks.

USD/CHF lost 45 pips to 0.9220.

AUD/USD increased 33 pips to 0.6988, as the Chinese government reported that fourth quarter gross domestic product grew 2.9% on year, above 1.5% expected.

USD/CAD dipped 17 pips to 1.3391. Canada's consumer price index rose 6.3% on year in December, below 6.4% expected.
 
MARKET COMMENTARY


On Wednesday, U.S. stocks closed in negative territory following retail and inflation data as the S&P 500 dropped 62.11pts (-1.56%) to 3928, the Nasdaq 100 decreased 146.9pts (-1.27%) to 11410 and the Dow Jones Industrial Average declined 613.89pts (-1.81%) to 33296.

Shares in the Food, Beverage & Tobacco (-2.93%), Banks (-2.72%), and Household & Personal Products (-2.57%) sectors underperformed the most during the trading session.

On the U.S. equity front, Microsoft (MSFT), the software development company, fell 1.89% to $235.81 as the company announced it will layoff 10,000 workers, roughly 5% of its workforce, through the end of the third-quarter of 2023. United Airlines (UAL), the transportation company, dropped 4.57% to $48.86 after posting an adjusted EPS forecast that beat estimates. IBM (IBM), an IT company, fell 3.29% to $140.41 after the stock was downgraded to "equal-weight" from "overweight" at Morgan Stanley.

Tesla (TSLA), the electric-vehicle maker, slid 2.06% to $128.78 as Elon Musk's Tweet trial continues. Tesla investor Glen Littleton is seeking damages on behalf of shareholders who bought the stock after Elon Musk tweeted his plans to take the company private back in August 2018. Also, Charles Schwab (SCHW), an investment brokerage group, dropped 2.53% to $81.38 on fourth-quarter adjusted EPS and revenue figures that fell short of expectations while Chegg (CHGG), the online educational platform, plunged 16.61% to $20.38 and underperformed the S&P 500 after the stock was downgraded to hold from buy at Needham.

Meanwhile, Moderna (MRNA), the biotechnological company, rose 3.32% to $197.02 following positive results from a trial of its respiratory syncytial virus (RSV) vaccine.

From a technical point of view, 3M (MMM -3.04% to $122.75), American Express (AXP -2.17% to $150.42), Chevron (CVX -1.81% to $177.23), Cisco Systems (CSCO -2.45% to $46.9), IBM (IBM -3.29% to $140.41), McDonald's (MCD -2.94% to $266.04), Microsoft (MSFT -1.89% to $235.81), and Procter & Gamble (PG -2.68% to $146.41) crossed under their 50-day moving average.

From a relative strength vs S&P 500 point of view, Intel (INTC -2.67% to $28.81) and Merck & Co (MRK -1.5% to $108.79) crossed under their 50-day moving average.

On the U.S. economic data front, December retail sales fell by 1.1% month over month, against an anticipated drop of 0.4%, while the Producer Prices Index increased by 6.2% year over year in December, compared to +6.9% expected. Also, December's industrial production slid by 0.7% on month, a bigger decline than the -0.3% forecasted, while business inventories grew 0.4% in November, vs +0.3% initially estimated. Meanwhile, the Federal Reserve sees US Price Growth moderating in 2023, according to their Beige Book.

The U.S. 10-year Treasury Yield dropped 17.6bps to 3.372%.

European stocks were mixed at the close. The Dax 40 fell 0.03%, while the Cac 40 rose 0.09% and the FTSE 100 declined 0.26%.

After the close of Wall Street, WTI Crude Future (FEB 23) was down $0.9 to $79.26. The contract was above its 20D MA (@ $77.31) and above its 50D MA (@ $78.79).

Gold was down $4.2 to $1904.5. The precious metal was above its 20D MA (@ $1852) and above its 50D MA (@ $1802).

Copper Future (MAR 23) on Comex was about flat to 422.3c/lb. The contract was above its 20D MA (@ 393.22c) and above its 50D MA (@ 382.14c). The 14d RSI above 70 (76.26) indicates Copper Future (MAR 23) contract was overbought.

Market Wrap: FOREX

The U.S. dollar index was relatively stable at 102.401.

EUR/USD rose 5pips to 1.0793.

GBP/USD added 58pips to 1.2344.

USD/JPY increased 68pips to 128.8.

AUD/USD fell 48pips to 0.694.

USD/CHF declined 57pips to 0.9164 and the USD/CAD jumped 107pips to 1.3496.

Bitcoin traded lower to 20770 while Ethereum decreased to 1527.

After Hours

No notable earnings or news were released after the market closed.
 
MARKET COMMENTARY


On Thursday, U.S. stocks closed lower for second session. The Dow Jones Industrial Average fell 252 points (-0.76%) to 33,044, the S&P 500 dropped 30 points (-0.76%) to 3,898, and the Nasdaq 100 was down 114 points (-1.00%) to 11,295.

The U.S. 10-year Treasury yield added 2.7 basis points to 3.397%.

Media (+1.12%) and energy (+1.11%) sectors gained the most, while semiconductors (-3.00%), capital goods (-2.45%) and household & personal products (-2.22%) sectors were under pressure.

Procter & Gamble (PG) declined 2.73%. The consumer-goods giant reported worse-than-expected decline in quarterly sales volume, sales and profit.

Alcoa (AA) sank 7.35% after the company posted lower-than-expected fourth-quarter earnings.

Roblox (RBLX) fell 6.57% as the stock was downgraded to "underweight" at Morgan Stanley.

On the other hand, Meta Platforms (META) rose 2.35%. JPMorgan said that the social technology company is better positioned than other peers ahead of its upcoming fourth-quarter results, and maintained an "overweight" rating for the stock.

Netflix (NFLX) ended 3.23% lower. In after-market hours, the stock rebounded over 3% after the company reported higher-than-expected growth in subscriber number in the fourth quarter. Also, co-founder Reed Hastings will step down as chief executive officer to become executive chairman.

Regarding U.S. economic data, the latest number of initial jobless claims fell to 190,000 (vs 207,000 expected).

The number of housing starts declined to an annualized rate of 1.38 million units in December (vs 1.40 million units expected). The Philadelphia Fed manufacturing index improved to -8.9 for January (vs -10.0 expected).

European stocks also closed lower. The DAX 40 fell 1.72%, the CAC 40 declined 1.86%, and the FTSE 100 lost 1.07%.

U.S. WTI crude futures gained $1.00 to $80.44 a barrel. The U.S. Energy Department reported an addition of 8.40 million barrels to the crude-oil stockpiles (vs a reduction of 0.59 million barrels expected).

Gold price shot up $28 to $1,932 an ounce.

The U.S. dollar softened against other major currencies, as economic data continued to signal a slowdown in the U.S. economy. The dollar index declined to 102.06.

EUR/USD increased 36 pips to 1.083.

USD/JPY dropped 50 pips to 128.40. This morning, Japan's data showed that the inflation rate rose to 4.0% on year in December (as expected).

GBP/USD gained 43 pips to 1.2391. This morning, the GfK U.K. consumer confidence index fell to -45 in January (vs -38 expected).

AUD/USD slid 33 pips to 0.6910.

USD/CHF declined 5 pips to 0.9158, and USD/CAD fell 30 pips to 1.3463.

Bitcoin remained resilient and regained the $21,000 level.
 
MARKET COMMENTARY


On Friday, U.S. stocks closed higher after declining for most of the week. The Dow Jones Industrial Average climbed 330 points (+1.00%) to 33,375, the S&P 500 rose 73 points (+1.89%) to 3,972, and the Nasdaq 100 jumped 323 points (+2.86%) to 11,619.

The U.S. 10-year Treasury yield rebounded a further 8.9 basis points to 3.481%.

Media (+4.61%), automobiles (+3.78%), and semiconductors (+3.51%) sectors gained the most.

NetFlix (NFLX) jumped 8.46% after the video-streaming company signed up more subscribers than expected in the fourth quarter. Also, company co-founder Reed Hastings will step down as chief executive.

Alphabet (GOOGL) rose 5.34% as the parent company of Google announced plans to cut about 12,000 jobs or over 6% of its global workforce.

Meanwhile, Tesla (TSLA) gained 4.91%, Nvidia (NVDA) jumped 6.41%, Amazon.com (AMZN) added 3.81%, Microsoft (MSFT) advanced 3.57%, and Apple (AAPL) was up 1.92%.

Regarding U.S. economic data, the number of existing-home sales dropped at an annualized rate of 1.5% on month in December (vs -2.0% expected).

European stocks also closed higher. The DAX 40 rose 0.76%, the CAC 40 gained 0.63%, and the FTSE 100 was up 0.30%.

U.S. WTI crude futures increased $1.20 to $81.84 a barrel, as investors turned optimistic on higher oil demand coming from China.

Gold price retreated $4 to $1,927 an ounce.

The U.S. dollar index dipped to 101.99.

EUR/USD added 24 pips to 1.0857. Germany's data showed that producer prices grew 21.8% on year in December (vs +19.9% expected, +28.2% in November).

USD/JPY surged 115 pips (+0.90%) to 129.58. Bank of Japan Governor Haruhiko Kuroda reiterated that the central bank will maintain its "extremely accommodative" monetary policy.

GBP/USD edged up 8 pips to 1.2399. U.K. data showed that retail sales declined 1.0% on month in December (vs +0.3% expected).

AUD/USD rose 63 pips to 0.6973.

USD/CHF gained 42 pips to 0.9203, while USD/CAD fell 89 pips to 1.3377.

Over the weekend, Bitcoin continued its recent rally striking $23,000, the highest level since August.
 
MARKET COMMENTARY


On Monday, U.S. stocks rebounded for a second session. The Dow Jones Industrial Average gained 254 points (+0.76%) to 33,629, the S&P 500 rose 47 points (+1.19%) to 4,019, and the Nasdaq 100 jumped 253 points (+2.18%) to 11,872.

Automobiles (+6.42%), semiconductors (+5.08%), and technology hardware & equipment (+2.25%) sectors were market leaders.

Electric-vehicle makers Tesla (TSLA), Nio Inc (NIO) and Rivian Automotive (RIVN) gained 7.74%, 8.94% and 11.52% respectively.

Advanced Micro Devices (AMD) jumped 9.22% and Qualcomm (QCOM) rose 6.62% after both semiconductor stocks were upgraded to "overweight" at Barclays.

Salesforce.com (CRM) rose 3.05% as activist investor Elliott Management bought a stake in the business-software developer.

Spotify Technology (SPOT) gained 2.07% after the music streaming specialist announced plans to cut its workforce by about 6%.

The U.S. 10-year Treasury yield added 3.7 basis points to 3.515%.

Regarding U.S. economic data, the Conference Board U.S. leading index declined 1.0% on month in December (vs -0.7% expected).

European stocks also closed higher. The DAX 40 rose 0.46%, the CAC 40 increased 0.51%, and the FTSE 100 was up 0.18%.

U.S. WTI crude futures were little changed at $81.62 a barrel.

Gold price gained $5 to $1,931 an ounce.

The U.S. dollar index remained stable at 102.03.

EUR/USD increased 16 pips to 1.0872.

USD/JPY jumped 107 pips to 130.67. This morning, the Jibun Bank Japan manufacturing purchasing managers index continued to post a contraction reading of 48.9 in January (vs 49.5 expected).

GBP/USD dropped 18 pips to 1.2379.

AUD/USD rose 66 pips to 0.7029. This morning, the National Australia Bank business confidence index posted at -1 for December (vs -2 expected).

USD/CHF gained 11 pips to 0.9217, while USD/CAD was down 14 pips to 1.3367 .

Bitcoin struggled to hold the $23,000 level.
 

Live Forex Chart

Currency
Rates
EUR / USD
1.14790
USD / JPY
156.877
GBP / USD
1.33950
USD / CHF
0.82250
USD / CAD
1.39985
EUR / JPY
180.080
AUD / USD
0.71320
Back
Top
Log in Register